
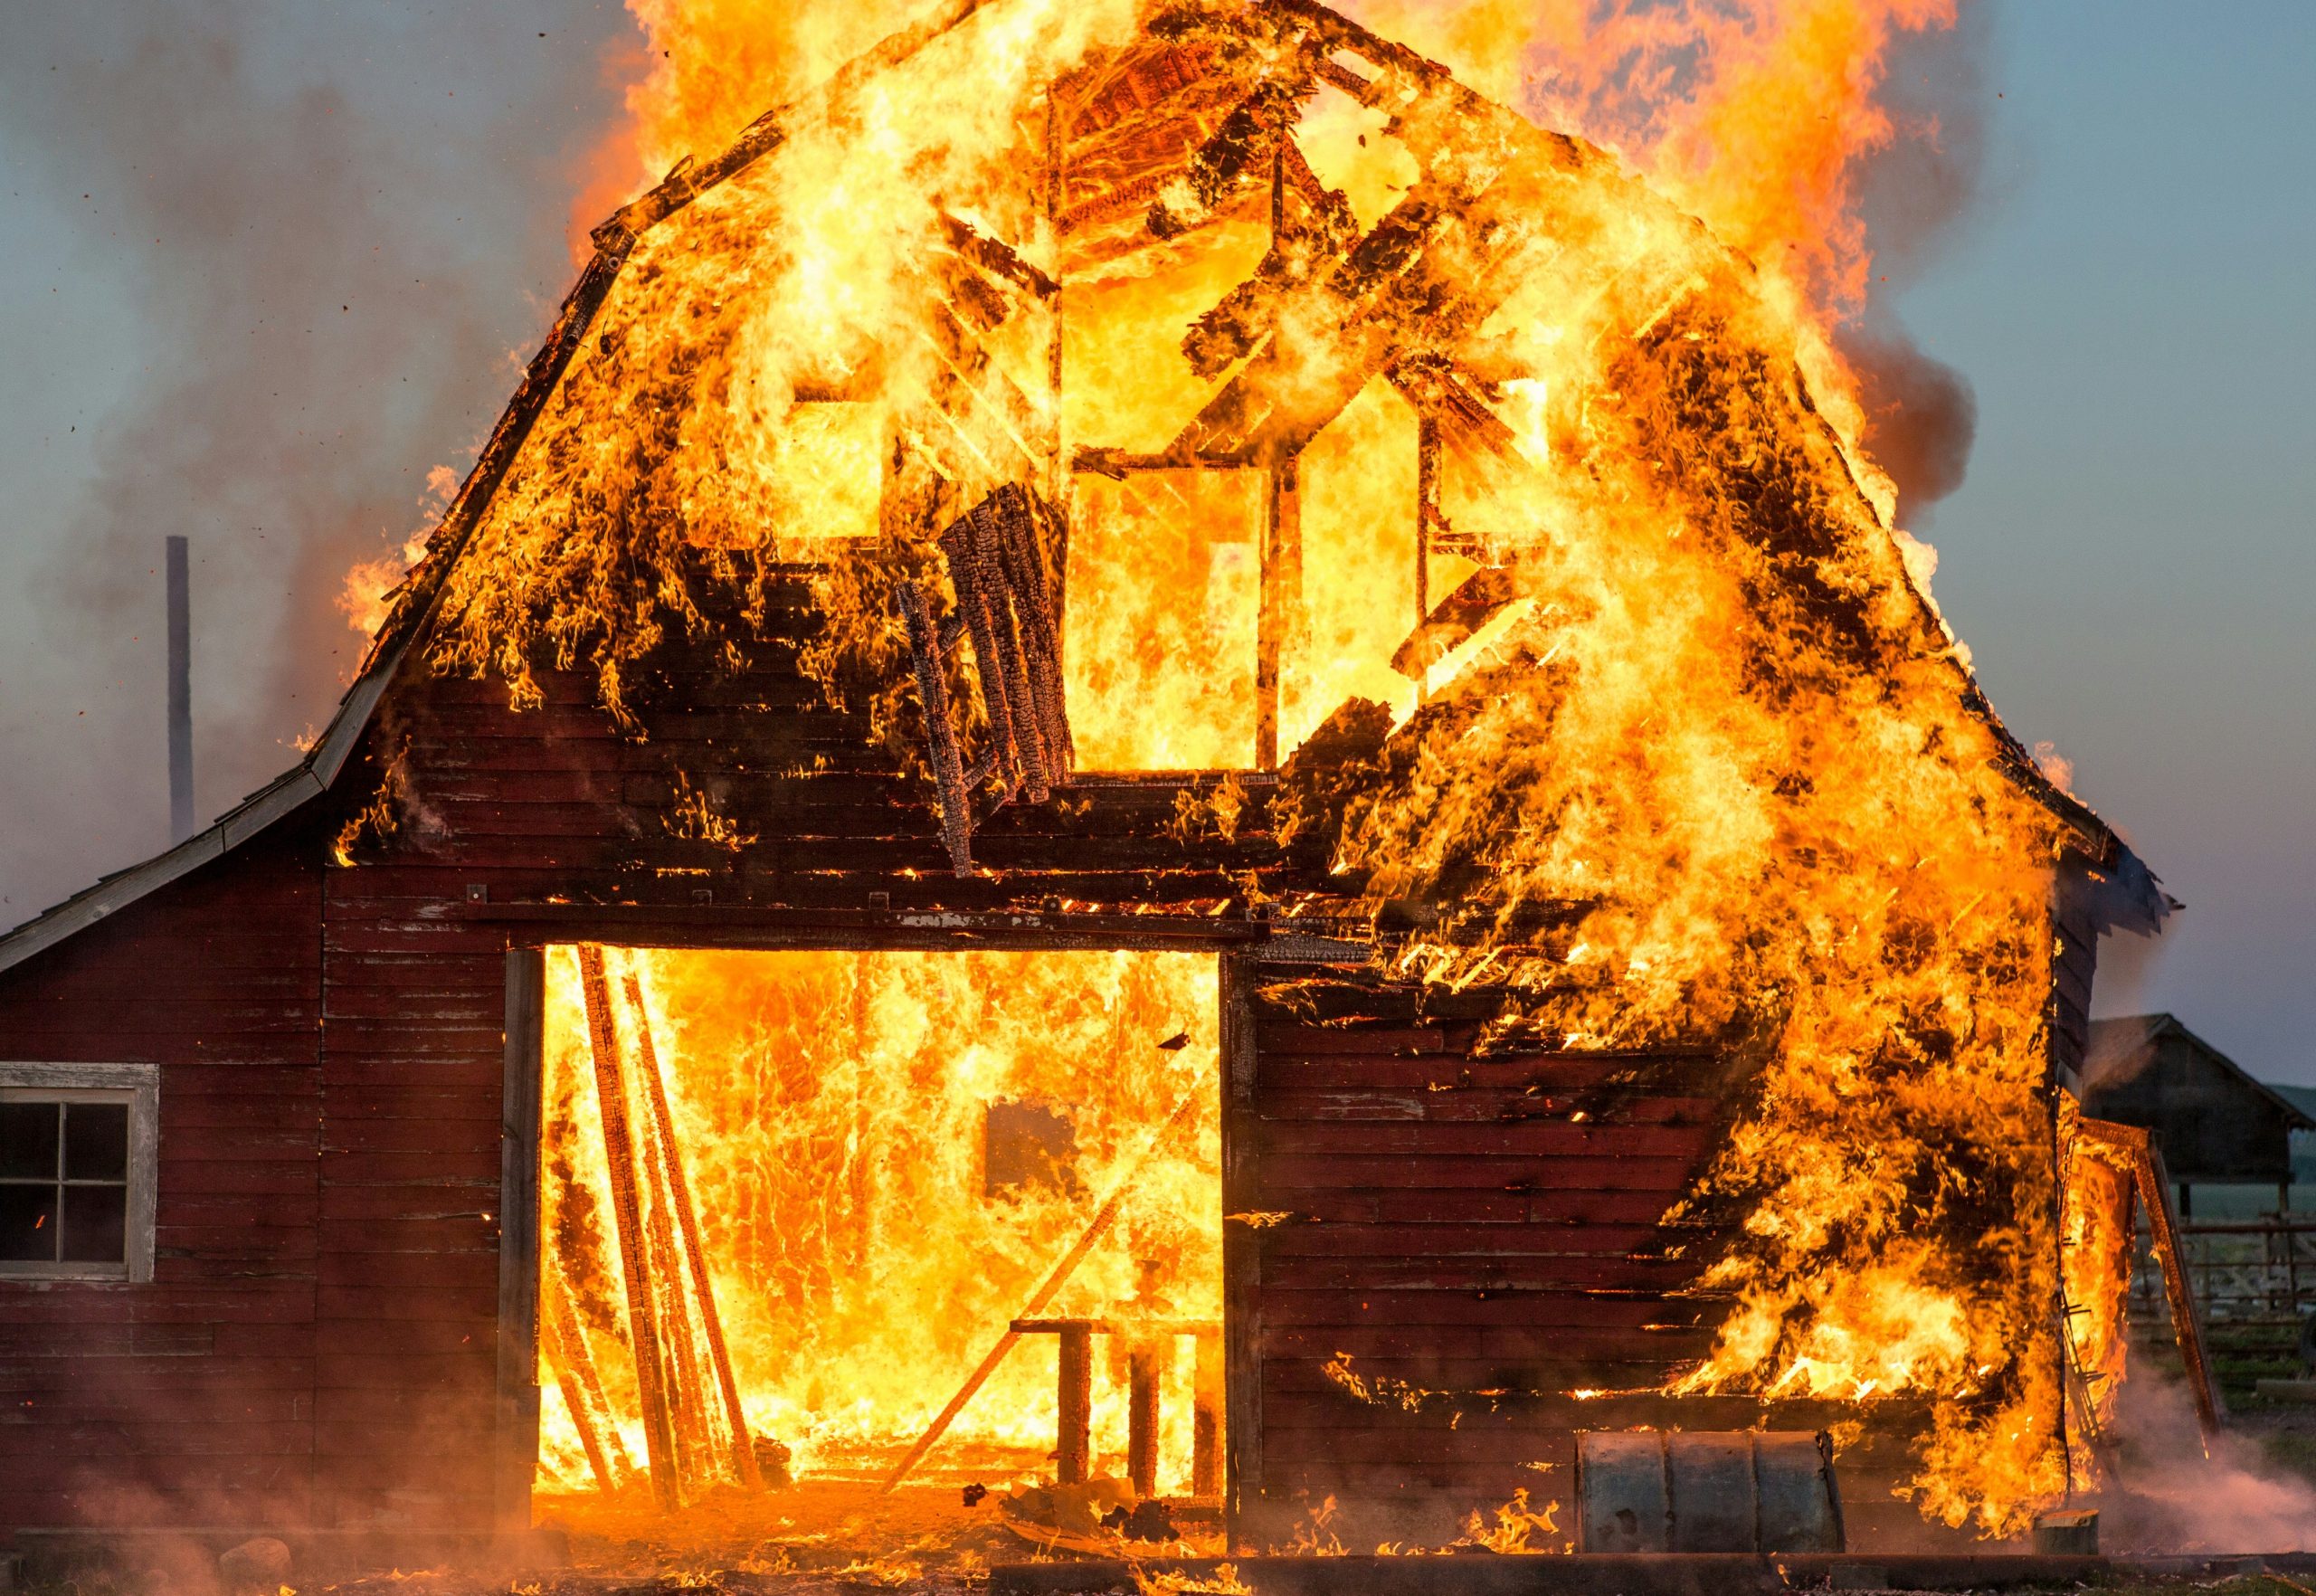
Filing a home insurance claim is stressful precisely when you’re already dealing with damage. Here’s a calm, step-by-step guide to doing it right and getting paid fairly.
- Make sure everyone is safe and prevent further damage first.
- Document everything thoroughly before you clean up or repair.
- Contact your insurer promptly and know your deductible.
- Small claims aren’t always worth filing — weigh them carefully.
When a storm damaged part of a family member’s roof, the claim went smoothly — not by luck, but because they knew the steps. I’ve also seen claims go badly simply because someone cleaned up too fast or waited too long. A little know-how makes an enormous difference.
Here’s exactly how to file a home insurance claim.
Step 1: Make sure everyone is safe
Before anything else, ensure your household is safe. If there’s structural damage, a gas leak, or electrical hazard, don’t take risks — get everyone out and call the relevant emergency services. No claim is worth anyone’s safety.
Step 2: Prevent further damage
Here’s a step people miss. Insurers generally expect you to take reasonable steps to stop the damage getting worse — like covering a broken window or shutting off water. Keep receipts for anything you buy to do this; those costs are often reimbursable. Just don’t make permanent repairs yet.
Temporary protective measures = good and expected. Permanent repairs before the adjuster sees the damage = a mistake. Document first, repair fully later.
Step 3: Document everything
This is where your claim is won or lost. Before cleaning up, capture thorough evidence:
- Photos and videos of all damage, from multiple angles.
- A list of damaged or destroyed items, with details.
- Proof of ownership — receipts, past photos, or records where possible.
- The cause, if known — a burst pipe, a fallen tree, a storm.
Knowing whether your type of damage is even covered helps here — our guides on water damage and roof damage explain what standard policies do and don’t cover.
Step 4: Contact your insurer promptly
Report the damage to your insurance company as soon as you reasonably can. Most have a claims line or app. Be honest and factual about what happened. Prompt, accurate reporting keeps your claim moving; delays and inconsistencies slow it down or raise questions.
Step 5: Understand your deductible and coverage
Before you count on a payout, know your deductible — the amount you pay before insurance covers the rest. If the damage barely exceeds it, filing may not be worth it. It also helps to know whether your policy pays replacement cost or actual cash value, since that affects how much you’ll receive. For the bigger picture, see how much home insurance you really need.
| Step | Why it matters |
|---|---|
| Ensure safety | People come before property |
| Prevent further damage | Expected by insurers; costs often reimbursed |
| Document thoroughly | Evidence drives your payout |
| Report promptly | Avoids delays and complications |
Step 6: Work with the adjuster
Your insurer will send an adjuster to assess the damage. Walk them through it, provide your documentation, and ask questions. This is where thorough photos pay off — strong evidence supports a fair assessment. The Insurance Information Institute outlines which disasters are typically covered, which helps you understand what the adjuster is evaluating.
Should you always file?
Honestly, no. Like auto claims, small home claims aren’t always worth filing — multiple claims can affect your future premiums, and a claim barely above your deductible may cost you more long-term than paying out of pocket. Weigh the payout against the potential impact before filing.
The bottom line
‘Run the numbers on your own situation before you sign.’: a home insurance claim goes best when you stay calm and methodical. Safety first, stop further damage, document everything before cleanup, report promptly, and know your deductible and coverage. Handle those steps well and you turn a stressful situation into a manageable one — with the fair payout you’re entitled to.
Save your insurer’s claims number and keep a simple home inventory with photos. When something goes wrong, having proof of what you owned makes the whole process far smoother.
Frequently asked questions
What should I do first after home damage?
Ensure everyone is safe, then take reasonable steps to prevent further damage — like covering a broken window. Document everything before cleaning up or making permanent repairs.
Should I file a claim for minor home damage?
Not always. If the cost barely exceeds your deductible, or if multiple claims could raise your premiums, paying out of pocket may be the better choice. Weigh it carefully.
How long do I have to file a home insurance claim?
File as soon as reasonably possible. Time limits vary, but prompt reporting helps your claim proceed smoothly and avoids complications that delays can cause.