
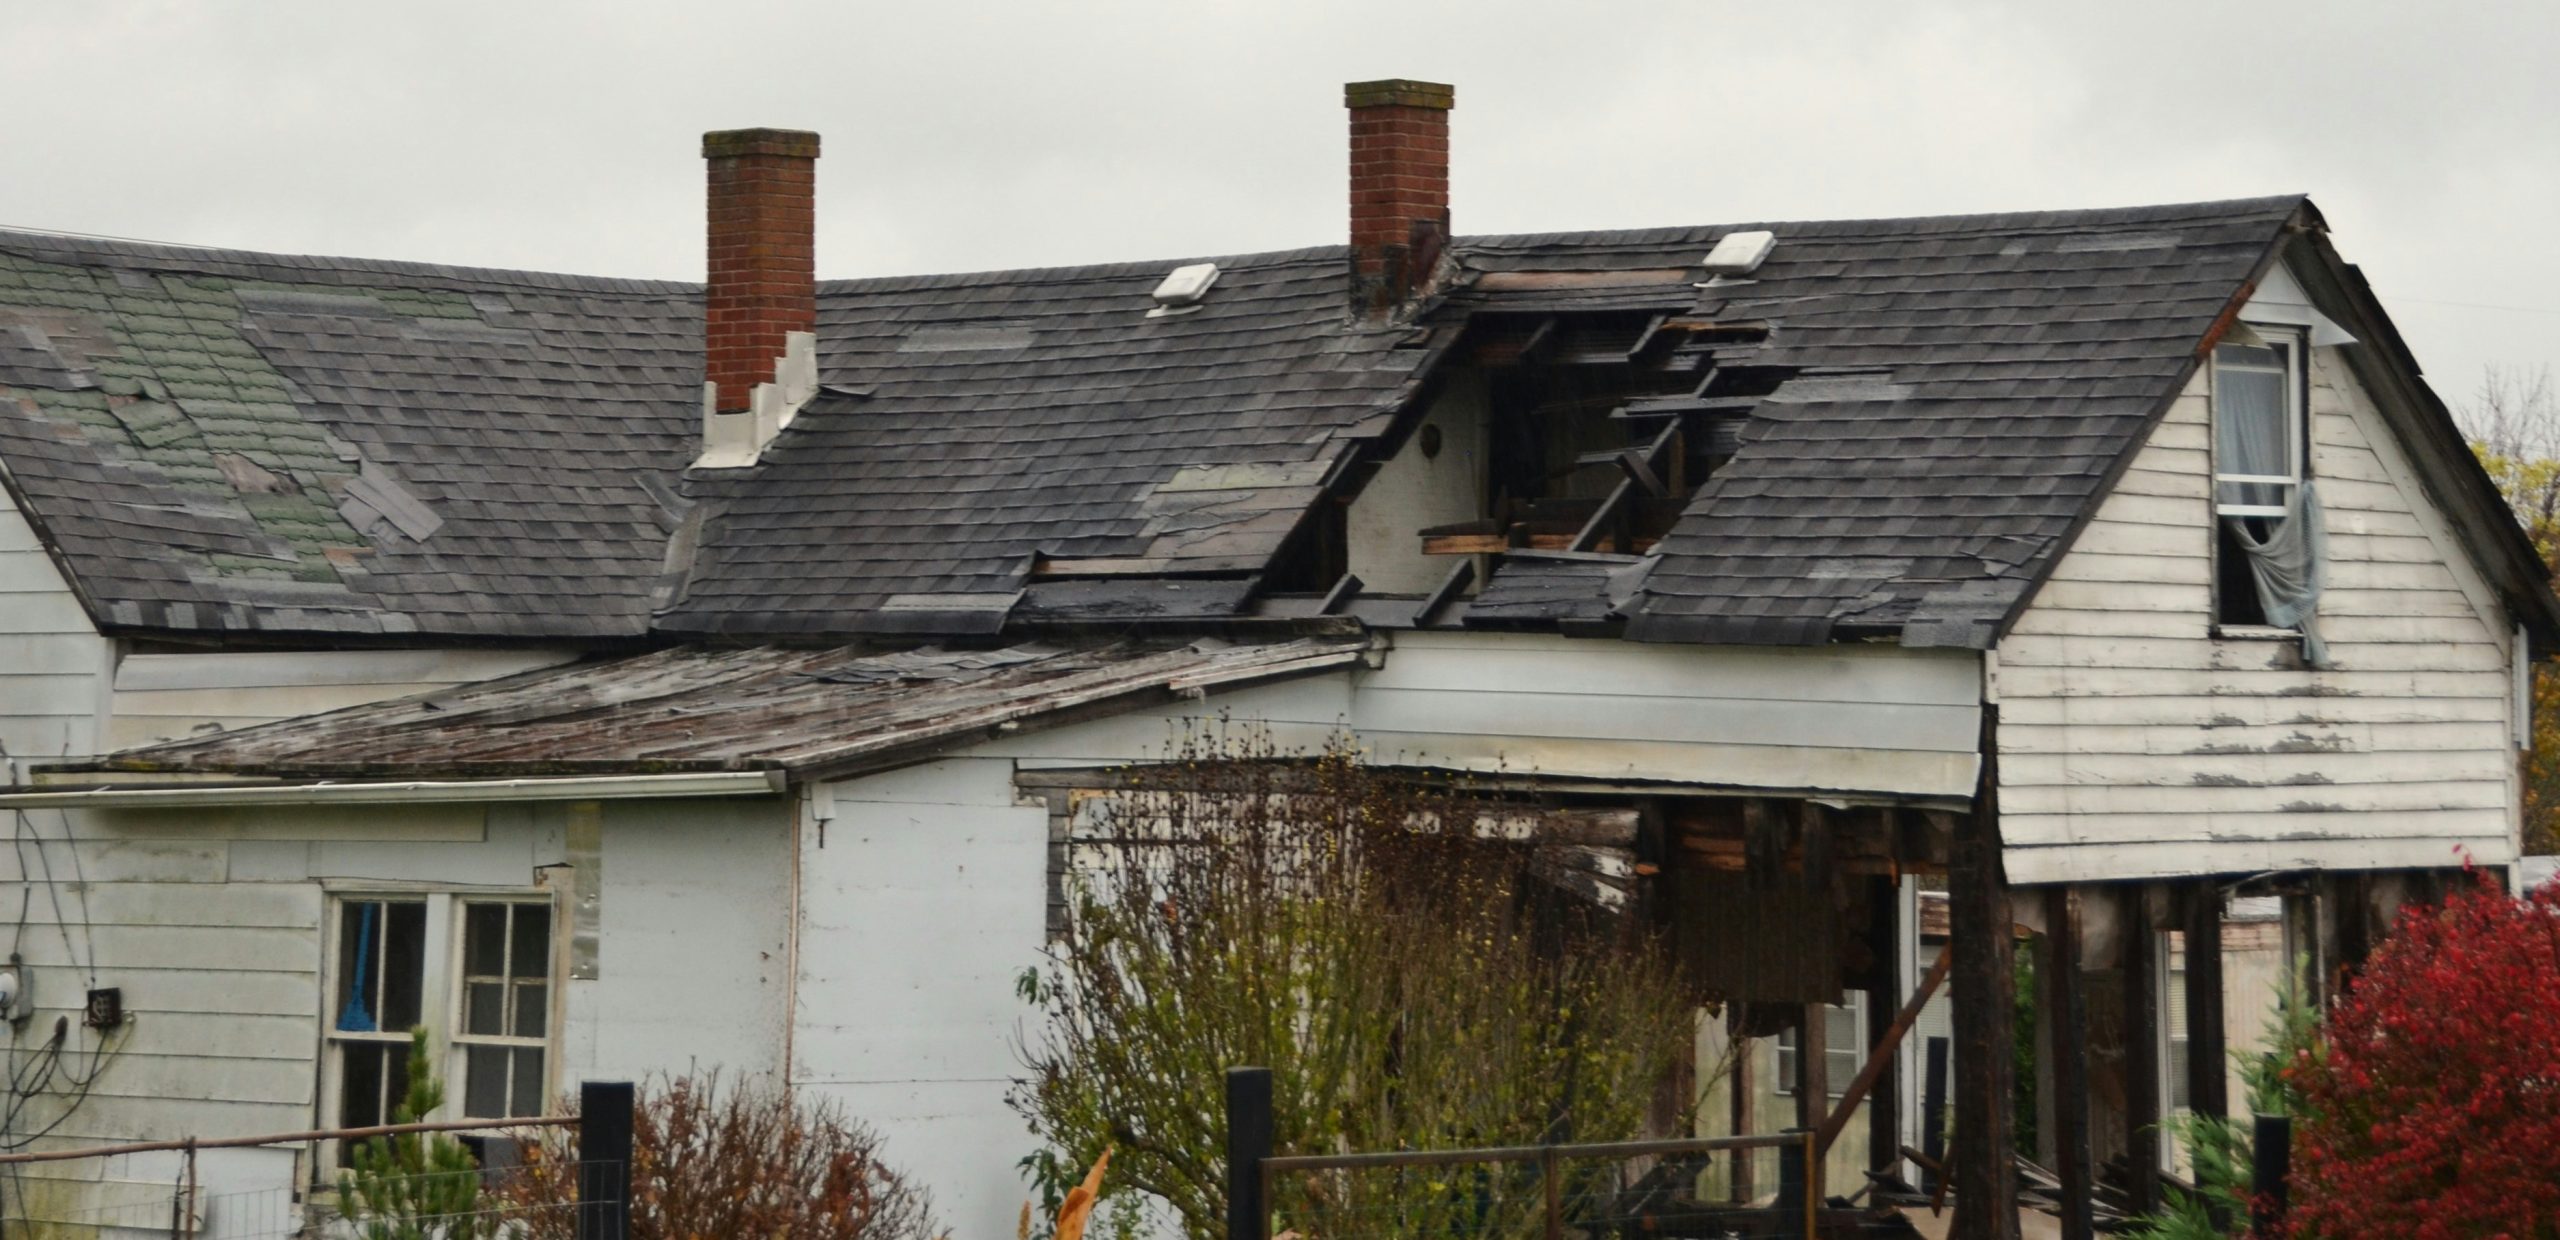
A damaged roof is one of the most expensive home repairs there is — so whether insurance covers it matters enormously. The answer comes down to cause and age.
- Sudden roof damage from storms or falling trees is usually covered.
- Damage from age, wear, or neglect is typically not covered.
- How your policy pays — replacement cost vs. depreciated value — matters a lot.
- Regular maintenance protects both your roof and your claim.
When a storm tore shingles off a neighbor’s roof, two houses had nearly identical damage — but only one claim got paid in full. The difference came down to the age of the roof and how each policy was written. That’s when I realized roof coverage isn’t a simple yes or no.
Here’s how to tell whether your roof is protected before you ever need to find out.
The two questions that decide everything
Roof coverage almost always comes down to two things: what caused the damage, and how old the roof is. Get both in your favor and you’re usually covered. Miss on either, and a claim can be reduced or denied.
What’s usually covered
Standard homeowners policies generally cover sudden, accidental roof damage from events like:
- Storms, wind, and hail.
- Falling trees or branches.
- Fire.
- Other sudden events named in your policy.
These fall under the same logic as most home claims — sudden and accidental damage from a covered peril. The Insurance Information Institute outlines which disasters standard policies do and don’t cover, which maps closely onto roof claims.
What’s usually NOT covered
Here’s where roof claims get denied. Standard policies typically won’t pay for:
- Age and wear — a roof simply reaching the end of its life.
- Neglect — damage that maintenance would have prevented.
- Gradual deterioration — slow problems that built up over years.
- Certain excluded events — like floods or earthquakes without added coverage.
Insurers expect a roof to be maintained. If an inspection shows the damage came from long-term wear rather than a sudden event, the claim can be denied — even after a storm.
Replacement cost vs. actual cash value
This detail can mean thousands of dollars, and most people don’t check it until it’s too late. Some policies pay replacement cost — what it costs to install a new roof today. Others pay actual cash value — that amount minus depreciation for the roof’s age. On an older roof, the depreciated payout can be dramatically lower.
| Payout type | What you get | Best for |
|---|---|---|
| Replacement cost | Full cost of a new roof | Better protection |
| Actual cash value | New cost minus depreciation | Cheaper premium, less payout |
How to protect your roof claim
A few habits keep you on the covered side of the line:
- Maintain your roof and fix small issues quickly.
- Keep records and photos of your roof’s condition over time.
- Know whether your policy pays replacement cost or actual cash value.
- Document storm damage immediately with photos before repairs.
Knowing your roof coverage is part of the bigger picture of insuring your home correctly — our guides on water damage coverage and how much home insurance you need round out the rest.
The bottom line
What I keep coming back to is this: your roof is usually covered when damage is sudden and the roof is well-maintained — and usually not when the real cause is age or neglect. The payout type matters just as much as the coverage itself, so check whether you have replacement cost or actual cash value now, not after a storm. Maintain the roof, know your policy, and document everything, and you’ll rarely be caught out.
Take dated photos of your roof in good condition. If damage happens later, that evidence helps prove it was sudden — not pre-existing wear.
Frequently asked questions
Does home insurance cover roof leaks?
It depends on the cause. A leak from sudden storm damage is usually covered, but a leak from age, wear, or neglected maintenance typically isn’t.
Will insurance replace an old roof?
Often only partially. If your policy pays actual cash value, an older roof’s payout is reduced by depreciation. Replacement cost coverage pays the full cost of a new roof.
Why was my roof claim denied?
Common reasons include damage caused by age or wear rather than a sudden event, poor maintenance, or an excluded peril. Insurers cover sudden, accidental damage, not gradual deterioration.