
Water damage is one of the most common home insurance claims — and one of the most misunderstood. Whether you’re covered depends entirely on where the water came from.
- Sudden, accidental water damage is usually covered; gradual damage often isn’t.
- Flooding from outside is almost never covered by standard policies.
- Flood coverage requires a separate flood insurance policy.
- Maintenance-related damage is typically excluded — upkeep matters.
When a pipe burst in a friend’s kitchen, his first panicked question was “am I even covered for this?” The honest answer to water damage is always the same frustrating phrase: it depends. But once you understand what it depends on, it actually becomes clear.
Here’s how to tell which water damage your policy covers — and which it doesn’t.
The key question: where did the water come from?
This is the whole thing in one sentence. Home insurance generally cares about the source of the water, not just the damage itself. Water that comes from a sudden, accidental problem inside your home is usually covered. Water that comes from outside, or from slow neglect, usually isn’t.
What’s usually covered
Standard policies typically cover water damage that’s sudden and accidental, such as:
- A burst pipe that floods a room.
- An overflowing washing machine or water heater failure.
- Rain coming in after a storm suddenly damages your roof.
- Accidental leaks from plumbing you couldn’t have foreseen.
The magic words insurers use are “sudden and accidental.” If the damage happened fast and unexpectedly, you’re usually in covered territory. If it built up slowly over months, you’re usually not.
What’s usually NOT covered
Here’s where people get caught out. Standard home insurance generally excludes:
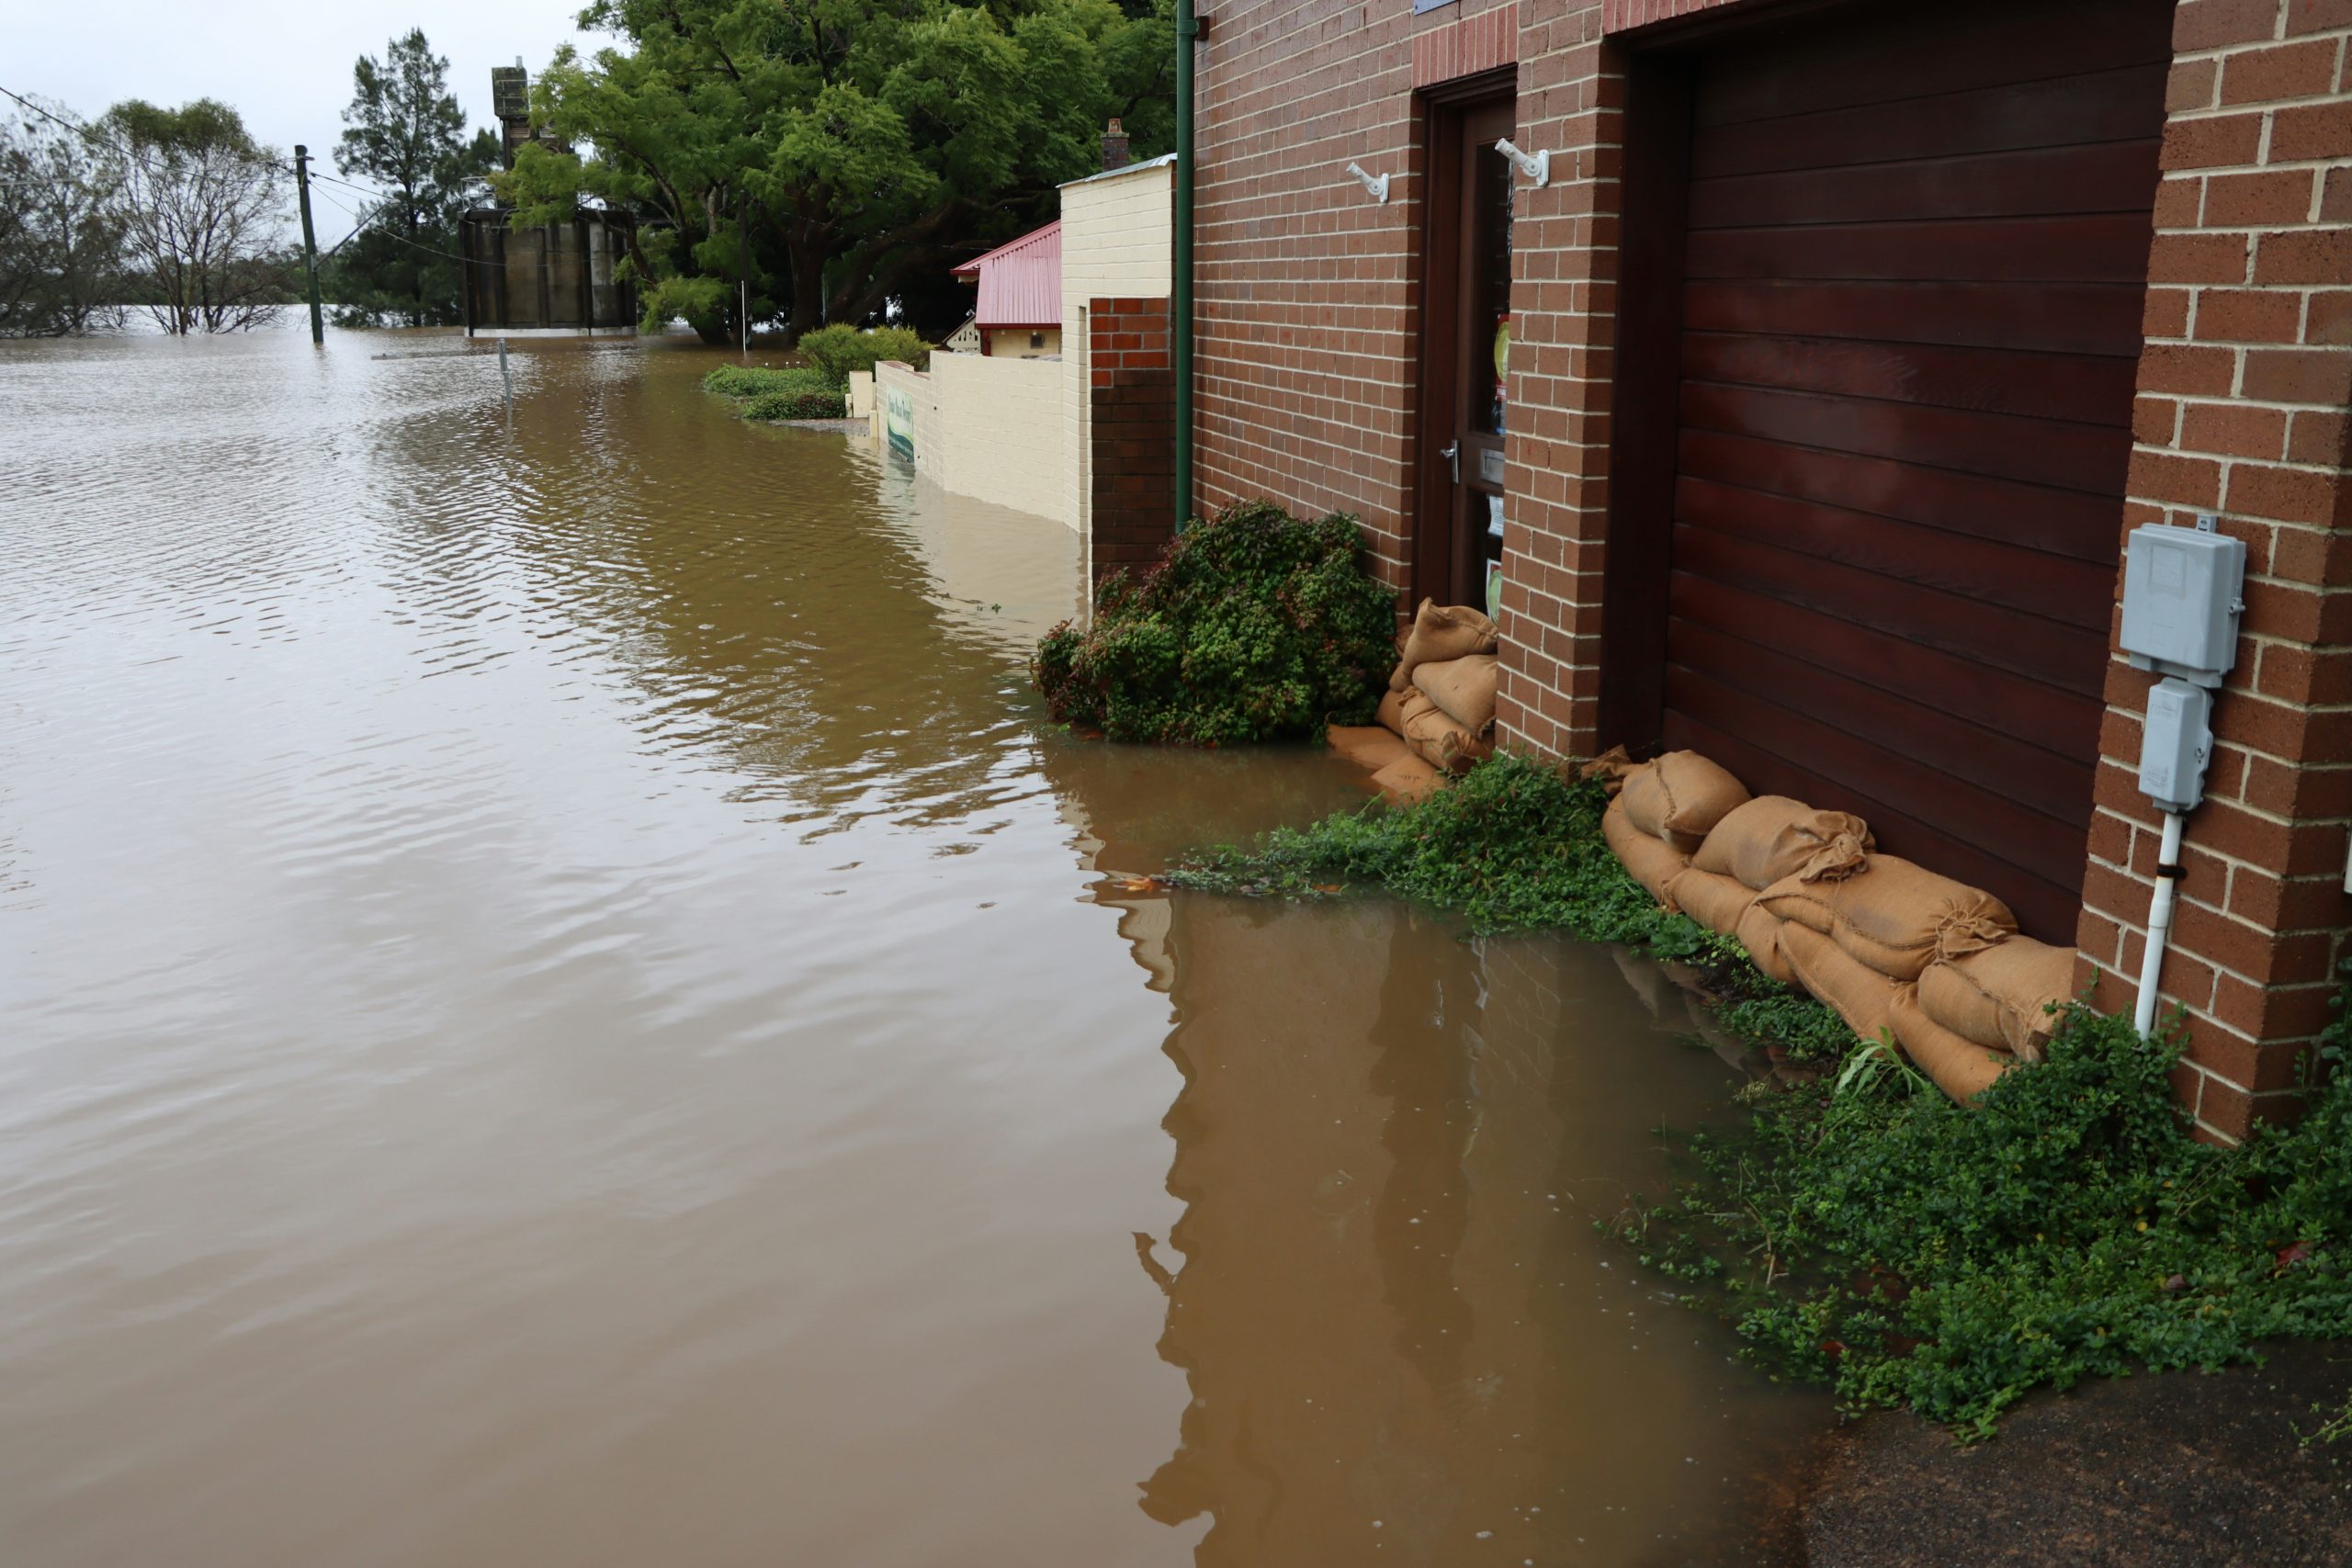
- Flooding from outside — rising water, storm surge, overflowing rivers.
- Gradual damage — a slow leak you ignored, or long-term seepage.
- Poor maintenance — damage that proper upkeep would have prevented.
- Sewer backups — often excluded unless you add specific coverage.
That flood exclusion is the big one. As the Insurance Information Institute explains, flood damage isn’t covered by standard homeowners policies and requires separate flood insurance. If you live anywhere with flood risk, this is not a detail to skip.
| Water source | Usually covered? |
|---|---|
| Burst pipe | Yes |
| Water heater failure | Yes |
| Flood from outside | No — needs flood insurance |
| Slow, ignored leak | No — gradual/maintenance |
| Sewer backup | Often no — needs add-on |
The maintenance trap
Here’s an honest warning. Insurers expect you to maintain your home, and they will deny claims for damage that good upkeep would have prevented. A pipe that burst overnight is one thing; a leak you noticed months ago and ignored is another. My advice: fix small water problems immediately, both to protect your home and to keep your coverage intact.
How to protect yourself
A few steps close most of the gaps:
- Add flood insurance if you’re in any flood-prone area.
- Ask about a sewer backup endorsement — it’s usually cheap.
- Keep up with maintenance and address leaks fast.
- Read your policy so you know your exclusions before a claim, not during one.
Knowing your coverage before disaster strikes is part of getting the amount right in the first place — our guide on how much home insurance you really need walks through the rest.
The bottom line
What I keep coming back to is this: with water damage, the source is everything. Sudden, accidental leaks from inside your home are usually covered; outside flooding and slow, neglected damage usually aren’t. Add flood coverage if you need it, stay on top of maintenance, and read your exclusions now — so that if water ever does come where it shouldn’t, you already know exactly where you stand.
Document water damage immediately with photos and videos, and stop further damage if you safely can. Good documentation makes claims go far more smoothly.
Frequently asked questions
Does home insurance cover a burst pipe?
Usually yes. Sudden, accidental water damage like a burst pipe is typically covered by standard homeowners insurance, as long as it wasn’t caused by neglected maintenance.
Does homeowners insurance cover flooding?
No. Flooding from outside sources is excluded from standard policies and requires separate flood insurance. If you’re in a flood-prone area, don’t assume you’re protected.
Why was my water damage claim denied?
Common reasons include gradual damage, poor maintenance, or flooding not covered by a standard policy. Insurers cover sudden, accidental damage — not problems that built up over time.